CareCredit's Fair Financing Principles lay out what you should know about each of our payment options, so you can choose the right fit for the care you want for yourself, your family and your pets.
Learn About Our Fair Financing Principles
The Principles outline what you should know before you apply, including the information providers in the CareCredit network are trained to share. The choice of how to pay is yours—and we want you to make it with confidence.
Synchrony's CareCredit credit card is used by 14 million people and accepted at more than 290,000 locations. CareCredit Pay Later is available at participating providers. Here's how each option works.
Fair Financing Principles
Include the following:
You deserve clear information about every CareCredit payment option available to you.
CareCredit is a credit card that can be used to pay for care, services and products that support your health and wellness goals, as well as your pets’ needs.
CareCredit is a credit card, not an-in-house financing offer from your provider. CareCredit is not an interest-free credit card.
CareCredit offers deferred interest financing for qualifying purchases of $200 or more with payment terms from 6, 12, 18 or 24 months. Interest will be charged to your account from the purchase date if the promotional purchase is not paid in full within the promotional period. Minimum Monthly Payments required.*
CareCredit offers reduced APR fixed-payment financing for qualifying purchases of $1,000 or more for 24, 36, 48 and 60 months, depending on the amount financed. The 60-month Fixed Payment Reduced APR promotion is only available for purchases of $2,500 or more.**
CareCredit Pay Later is a single-use installment loan that offers eligible consumers a fixed APR, fixed monthly payments, and a defined payoff timeline to budget for specific health and wellness expenses.
Visit CareCredit’s Payment Calculator to help estimate your monthly payments based on the amount you’d like to finance and the promotional financing option you choose. This tool can help you know what payments to expect before applying for a CareCredit credit card.
You deserve simple and transparent information from your provider.
That's why Synchrony requires at least one person at every provider location offering CareCredit to complete CareCredit Certification Training and train others in the office on how to discuss CareCredit with you. Recertification is required every two years.
Along with what you hear from your provider, you can review the full terms and conditions anytime before you apply. They're included on the application and available in the CareCredit mobile app and on carecredit.com. We encourage you to read them carefully before you apply.
You deserve to know the estimated costs of the health and wellness care, products or services you’re seeking.
Your provider should share, in writing, the cost of any care, product or service with you, including the amount that may be paid by your insurance.
You deserve to understand the details of your financing options before you apply.
Here are questions to ask before you decide which option is right for you.
If you're considering a credit card promotion:
What type of promotion is it: deferred interest or reduced fixed APR?
What is the required payment schedule?
Does paying only the minimum balance ensure you pay it off before the promotional period ends?
When does the promotion end?
If it’s a deferred interest promotion, what happens if you haven't paid the promotional balance in full before the end date?*
If you're considering CareCredit Pay Later:
How long is the loan term?
What is the fixed APR?
What will your monthly payment be and when is your final payment due?
You deserve a monthly statement that clearly shows your balance and its terms.
Your statement will show you:
If you have a credit card promotion:
How much of the promotional balance remains.
What minimum payment is required. Keep in mind that paying only the minimum may not pay off the promotional balance before the promotional period ends.
When the promotional period ends.
The interest that has accrued to date, which will be charged if you don't pay the promotional balance in full before the promotional period ends.
Tip: To estimate a monthly payment that pays off a deferred interest purchase before the promotional period ends, divide the purchase amount by the number of months in the promotional period. Paying that amount each month can help you pay the balance in full before the promotion ends.
If you have a CareCredit Pay Later loan:
How much of the loan balance remains.
Your monthly payment amount and due date.
How many payments remain, or your final payment date.
You deserve an easy way to share feedback with us.
We'd like to hear how your experience applying for and using CareCredit went, whether it's praise for great service or ideas on how we can do better. Contact us or call us at (866) 893-7864.
Hear more from providers in the CareCredit network
5 Things to Consider When Preparing for Out-of-Pocket Healthcare Costs
There are a number of ways to pay for health and wellness care, services and products. You are encouraged to maximize your options before applying for the CareCredit credit card.
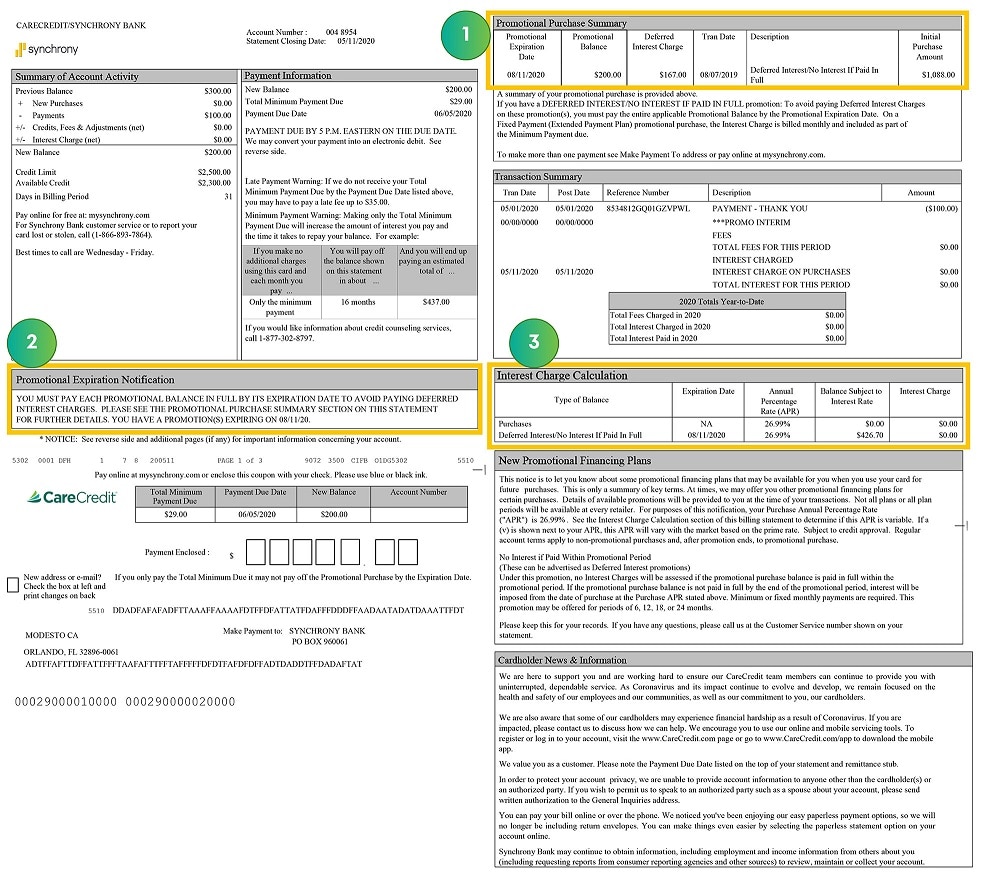
Details on your promotional purchase(s) can be found here, including the respective promotional period expiration date(s), the promotional balance(s) and the deferred interest accrued for each promotional purchase for the statement period.
For statements with multiple promotional purchases, each transaction will appear here with the corresponding details.
Promotional Expiration Notice
Deferred interest promotion expiration date(s) and reminder to pay the balance(s) off in full before that date in order to avoid paying the deferred interest charges.
If you have multiple promotions expiring, each expiration notice will be included here.
Interest Charge Calculation
Shows the APR, interest charges, and expiration date for each type of transaction, including multiple promotional finance purchases.
For statements with promotional purchases, each transaction will appear here with its corresponding information.
I have dental insurance through my job... But a root canal, it didn't cover that.
Dental
Eric D.
I have dental insurance through my job... But a root canal, it didn't cover that.
/
FAQs
The CareCredit Fair Financing Principles are grounded in our mission to responsibly provide clear and transparent payment options to help you pay for health and wellness costs over time (including pet care) so you can receive the care, services and products you want at locations in the CareCredit network. The principles have been a foundational aspect of our business and help to ensure clarity and transparency for current and prospective cardholders. These Principles are inclusive of the information that our providers are trained to share about CareCredit’s financing offers. Specifically, it outlines what you should know before applying for a CareCredit credit card.
We recommend that anyone interested in learning more about our promotional offers and how they work start by visiting CareCredit’s Fair Financing Principles page. This page outlines how deferred interest and reduced APR offers work, includes questions for consumers to consider to help them understand key aspects of the offer, a payment calculator, a financial glossary of terms and much more.
Consumers can also visit CareCredit’s Well U page for articles on financial health, health and wellness, and even pet care, including tips for prioritizing your health, information on popular procedures, and various options to pay for health and wellness costs.
Providers value their patient relationships and the trust they have built above all else and are committed to ensuring their patients are fully educated on CareCredit financing options and how they work. While over 70% of CareCredit cardholders apply for the credit card directly on the CareCredit website, many value the direct conversation with their provider’s office staff.
We recommend you complete the CareCredit application yourself and that you fully understand how the promotional financing options work.
To uphold these principles, we know training is essential. CareCredit requires training and offers provider support.
· Anyone who speaks with patients about the CareCredit credit card must be trained.
· Additionally, CareCredit offers all providers a wide range of resources, from reference materials, training courses, on-site and phone support, account management support and financial conversation coaching.
· CareCredit supports providers as they communicate with their patients about flexible financing options by offering standardized information and materials, online content, emails, communication through our mobile app, and more.
· We continually update and share new resources to ensure providers deliver best-in-class, clear and transparent communication about CareCredit, and are upholding the Fair Financing Principles.
· Providers offering the CareCredit credit card are monitored for cardholder complaints and dispute activity. If a pattern is established where a provider is not sharing clear and transparent information, providers and/or their office personnel will be asked to retrain. For recurring or egregious issues, CareCredit may terminate the ability for that provider to offer our financing solutions.
· CareCredit is not an in-house financing offer. It is a credit card that can be used to pay for care, services and products that support your health and wellness goals (including for your pets).
· CareCredit is not an interest-free credit card.
Be sure you understand the following, which can be explained by your provider or their office staff, before you apply:
· The length of a promotional period, including deferred interest or long-term payment schedules and applicable interest rate.
· When the promotional period expires and what happens if you do not pay the balance in full by the end of the promotional period.
· The required minimum payment amounts during the promotional period.
· When discussing a deferred interest offer, it is important to note that interest accrues on the outstanding promotional balance during the promotional period from the date of the transaction. Paying interest can be avoided ONLY IF the balance is paid off BEFORE the end of the promotional period.
· For answers to these questions and others, you can contact CareCredit or call the number on the back of your CareCredit credit card. We are available every day from 8:00am – 12:00am midnight (EST).
After using your CareCredit credit card to make a promotional purchase, you will receive a receipt for your transaction that includes a description of the promotion, the length of the promotional period, how deferred interest works (if applicable), and other promotion terms.
For deferred interest financing, within 3 days of applying for a CareCredit credit card through your provider and making a deferred interest purchase on the same day, you will receive a call or text from CareCredit to provide information about how deferred interest works. In addition, monthly billing statements will always show the following:
· The minimum monthly payment amount and due date to avoid a late payment charge. Keep in mind that making only the minimum payment required by your monthly statement may or may not pay off the promotional purchase within the promotional period. If you would like to estimate a monthly payment amount that would pay off the full amount of the promotional purchase within the promotional period, divide your promotional purchase amount by the number of months you have left on the promotional period.
· The total payment you need to make in order to pay off your balance before the end of the promotional financing period.
· The amount of interest accrued up to the last payment period and owed if you do not pay off the full amount of the deferred interest promotional balance before the promotional period ends.
· When the account is at 60 days and then 30 days before the end of the promotional period, you will see a note on the first page of your statement reminding you of the final promotional period end date.
If you are a cardholder and have questions about your account you can contact CareCredit here or call the number on the back of your CareCredit credit card. We are available Monday through Sunday from 8:00am – 12:00am midnight (ET).
If you want to apply, click here or call (800) 677-0718.*** Find out immediately if you have been approved by using our easy, automated system anytime or applying with a live agent 24/7 365 days a year.
CareCredit Pay Later is a single-use installment loan that offers eligible consumers a fixed APR, fixed monthly payments and a defined payoff timeline to budget for specific health and wellness expenses. The loan closes once the balance is paid in full.
CareCredit Pay Later is a single-use installment loan that closes once the balance is paid in full. The CareCredit credit card is a reusable line of credit with promotional financing options, including deferred interest and reduced APR plans, and it can be used again across more than 290,000 provider and retail locations nationwide.
No. You can see if you prequalify for CareCredit financing options with a simple pre-application with no hard credit check, meaning there is no impact to your credit score. If you accept an offer and submit a full application, a hard credit inquiry will be made, which may affect your credit score.
CareCredit Pay Later is available at participating health and wellness locations, including select dental, cosmetic, vision and audiology providers, with plans to expand across the CareCredit network over time. Ask your provider which CareCredit payment options are available at their practice.
CareCredit Pay Later is designed as a single-use loan for a specific treatment, service or product. For routine visits, ongoing care or repeat purchases across the CareCredit network, the reusable CareCredit credit card may be a better fit.
Yes. CareCredit uses Synchrony PRISM® when reviewing applications, an advanced underwriting engine that looks at your broader financial picture. PRISM evaluates your overall active debt commitments, including active loans across other platforms. This is designed to help avoid taking on payments you can't comfortably manage.
*No interest will be charged on the promo balance if you pay it off, in full, within the promo period. If you do not, interest will be charged on the promo balance from the purchase date. The required minimum monthly payments may or may not pay off the promo balance before the end of the promo period, depending on purchase amount, promo length and payment allocation. Regular account terms apply to non-promo purchases and, after promo period ends, to the promo balance. For New Accounts as of 5/30/2024: Purchase APR 32.99%. Penalty APR 39.99%. Min Interest Charge $2. CareCredit Rewards Mastercard: Cash APR 32.99% and 4% Fee ($10 min). Bal Trans APR 32.99% and 5% Fee ($5 min). Foreign Trans Fee 3%.Existing cardholders: See your credit card agreement terms. Subject to credit approval.
**Interest will be charged on promo purchases at a reduced APR from the purchase date. Fixed monthly payments are required until paid in full and will be calculated as follows: on 24-month promotions 4.9876% of initial promo purchase amount; on 36-month promotions 3.6605% of initial promo purchase amount; on 48-month promotions 3.0377% of initial promo purchase amount or on 60-month promotion 2.6997% of initial promo purchase amount. The fixed monthly payment will be rounded up to the next highest whole dollar and may be higher than the minimum payment that would be required if the purchase was a non-promo purchase. During the last month(s) of the promo period the required monthly payment may be reduced due to the prior months’ rounding. Regular account terms apply to non-promo purchases. For New Accounts as of 5/30/2024: Purchase APR 32.99%. Penalty APR 39.99%. Min Interest Charge $2. CareCredit Rewards Mastercard: Cash APR 32.99% and 4% Fee ($10 min). Bal Trans APR 32.99% and 5% Fee ($5 min). Foreign Trans Fee 3%. Existing cardholders: See your credit card agreement terms. Subject to credit approval.
*** Phone applications are only for the CareCredit credit card. To also be considered for the CareCredit Rewards Mastercard® please apply online. Must be 18+ to apply. Must be 21+ to apply by phone.
1 Actual cost may vary based on geography, provider and other variables. Cost information is based on research in the 50 United States and the District of Columbia, which was conducted by ASQ360° in 2023-2026 on behalf of Synchrony’s CareCredit.
 Search


 VIDEO



 ARTICLE




 Dental


